

After I proposed a £1 billion annual capital grant scheme for machine tools, several people politely pushed back. They argued that subsidies are, at best, a distraction from more important supply-side reforms.
There is now a large group of intelligent people in Britain who agree that economic stagnation is the country’s central problem and that reversing it will require major reforms. But there is also a divide over how those reforms should happen.
Many on the centre-right and right are understandably sceptical of targeted government intervention in industry. They oppose policies such as capital grants, nationalising British Steel, or imposing tariffs and quotas on specific products.
Instead, they favour broader supply-side reforms: cheaper energy, planning deregulation, housing liberalisation, and lower taxes to encourage business investment. Industrial policy is often viewed as either a distraction from these priorities or a misallocation of resources.
This view is coherent, serious, and in many respects correct. Britain does suffer from extraordinarily high energy costs, a dysfunctional planning system, and a tax structure that often penalises investment. Fixing these issues would improve economic performance.
But I increasingly think there is a mistake in assuming that horizontal reforms alone are sufficient to rebuild industrial capacity.
Britain’s problem is not simply that the general business environment is weak. It is also that the country has lost specific forms of productive capability over decades: machine tools, steelmaking, chemicals, advanced manufacturing supply chains, and the tacit industrial knowledge that sits behind them.
Once these ecosystems disappear, they do not automatically re-emerge simply because the corporate tax rate falls or planning permission becomes easier to obtain.
Industrial capacity is path dependent. Countries that retain manufacturing depth tend to do so because they continuously reproduce it through investment, procurement, training, and, in many cases, deliberate state support.
This is one reason why countries often admired by the British pro-growth right — such as Germany, South Korea, or even the United States — have historically combined broad market reforms with targeted industrial policy.
KfW in Germany, for example, was not created because German policymakers believed free markets were unimportant. It existed because they understood that capital-intensive industries often require long-term financing structures that private markets struggle to provide consistently.
The same logic applies to capital grants for machine tools. The point is not that subsidies are universally good, or that government planners can micromanage industrial development. The point is that Britain has underinvested in productive capital for so long that relying solely on indirect incentives may simply be too slow.
If a relatively modest annual grant programme encourages firms to modernise equipment, expand domestic production capability, and increase investment intensity, then it should complement wider supply-side reforms rather than substitute for them.
The real question is not whether Britain should choose between supply-side reform and industrial policy. It is whether the country can realistically reverse decades of industrial decline without using both.
Industrial policy is currently poor.
Much of what the free-market reformers say is right. Britain is clearly not a supply-side paradise. The sclerosis of the planning system is well documented, energy is a total disaster, and taxes are increasing as a share of GDP.
It’s also true that modern British industrial policy is not well thought out. I talked to a bright young civil servant tangentially involved in the making of the last industrial policy paper, and he described how every department lobbied to get its little fiefdom included.
The result is a bloated document with limited focus. The ‘strategy’ prioritises six sectors, which cover 35% of all employment. Of those jobs, 77% are in the creative industries, Digital and Technologies, and Professional and Business Services. These sectors have an average GVA per worker lower than the national average (£77,000).
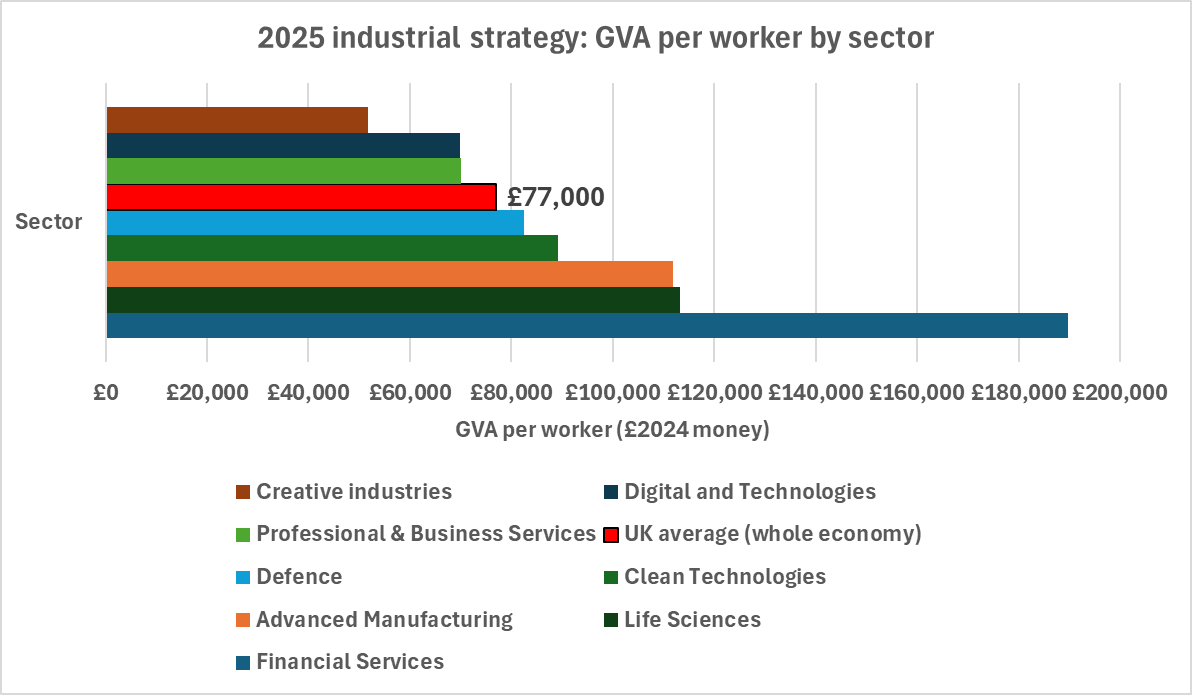
Figure 1: GVA per worker for sectors covered by the 2025 Industrial Policy Paper. Source: GOV.UK.
Now, there might very well be a reason to target improving productivity in low-productivity sectors, as highlighted here by the academic Jun Du. However, I think this is distinct from the traditional aim of industrial policy, which is shifting the workforce from structurally low-productivity sectors to high-productivity sectors, which also matter for technological capability and national power projection. If we are going to try to make construction and the NHS more productive, that is quite distinct from the desire to improve our diminishing position in manufacturing.
British industrial policy fails partly because it tries to promise everything to everyone. Decarbonisation gets mixed with regional redistribution, which gets mixed with job creation, which gets mixed with desires to be an innovation superpower in the most speculative technologies, with quantum computing being a clear example. What never gets defined is what size the industrial economy should be, how much growth can be expected, or what share of employment and output manufacturing should represent. We have a panoply of desires with no clear mission.
Instead, small amounts of money are spread thinly across the country, with little willingness to make difficult decisions about where industry should actually be concentrated. Because Britain’s housing market is so constrained, policymakers rarely even consider large-scale internal migration towards productive industrial regions. Instead, struggling areas receive scattered subsidies with no broader strategy behind them.
The UK also misses another key component of industrial policy. It only works in the context of a wider political economy. In Taiwan, China, Japan, Germany and Sweden, industrial policy is directed through a partnership, implied or otherwise, between the government and powerful domestic industrial conglomerates. In many cases, the industrial elite of those countries have power and political influence far exceeding that of British billionaires. The Wallenbergs of Sweden, the myriad industrial foundations in Germany, the keiretsu and the chaebols all continue to wield significant influence.
Industrial policy is often seen as an alternative to markets and the power of the wealthy. The truth is that successful industrial policy is historically a compromise between the wealthy and their societies; you are given government support, protection and priority, and in return, you invest domestically and think beyond immediate shareholder returns. To some, this is a grubby relationship, but we already accept it on a small scale, whether it’s Anthony Bamford’s donations or the government supporting Jim Ratcliffe.
Britain no longer has many large, domestically owned industrial firms capable of competing globally. Our car industry is now almost entirely foreign-owned. This may help headline productivity figures, but foreign firms generally prioritise their home markets and domestic supply chains.
So to summarise, much of our industrial policy is flawed. However, it is also worth noting that supply-side reform has already been enacted, and the more ambitious elements of it are politically contentious.
Supply-side reform is necessary, but not a panacea.
The immediate supply-side alternative to direct investment or grants is tax exemptions in the form of credits or full expensing. In the early 1970s, the incoming Tory government replaced grants with tax deductions, on the basis that they were more market-friendly. Today, we have implemented a fair range of tax-cutting measures to stimulate capital investment, with little success. Full expensing has not seen a significant increase in investment. As shown below, manufacturing private sector investment has fallen since 2023, when full expensing came into effect.
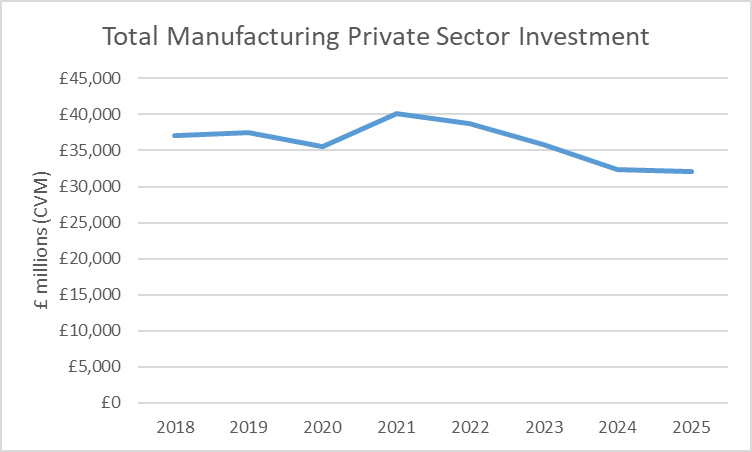
Figure 2: Manufacturing private investment 2018 to 2025 (CVM). Full expensing comes into effect in April 2023. Source: ONS.
Meanwhile, the R&D tax credit scheme in the UK is among the most generous in the world. Fully 0.33% of GDP goes towards tax incentives to R&D, far more than is the case for the OECD average (0.12%).
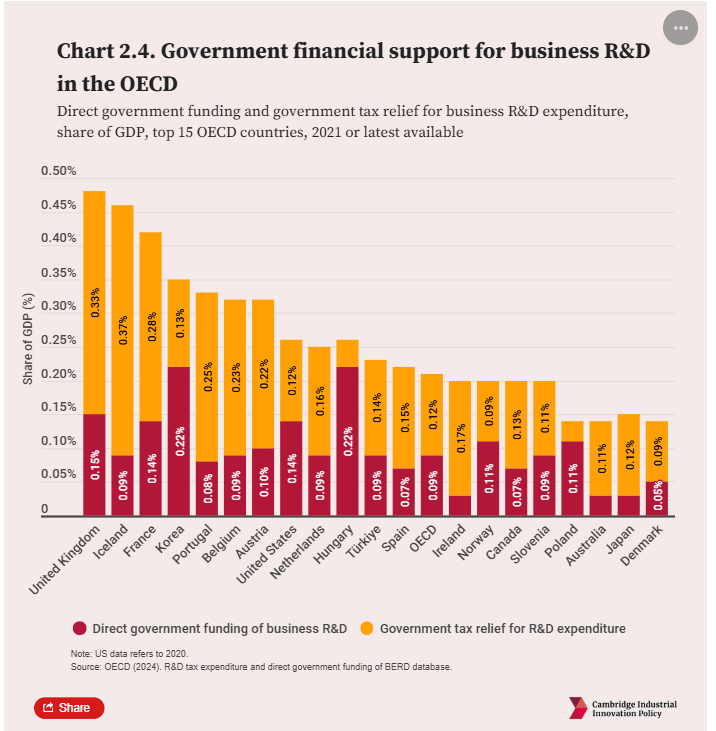
Figure 3: Government financial support for business R&D in G7 countries: Source.
It is not clear whether this is generating desirable R&D investment. Despite manufacturing accounting for 50% of R&D spending, the vast majority of R&D tax credits go to services, including such hotbeds of Promethean potential as ‘office administration and business support activities.’ There’s a good chance these reliefs are just being used by creative accountants to create small cuts in corporation tax, and are a net loss for the country.
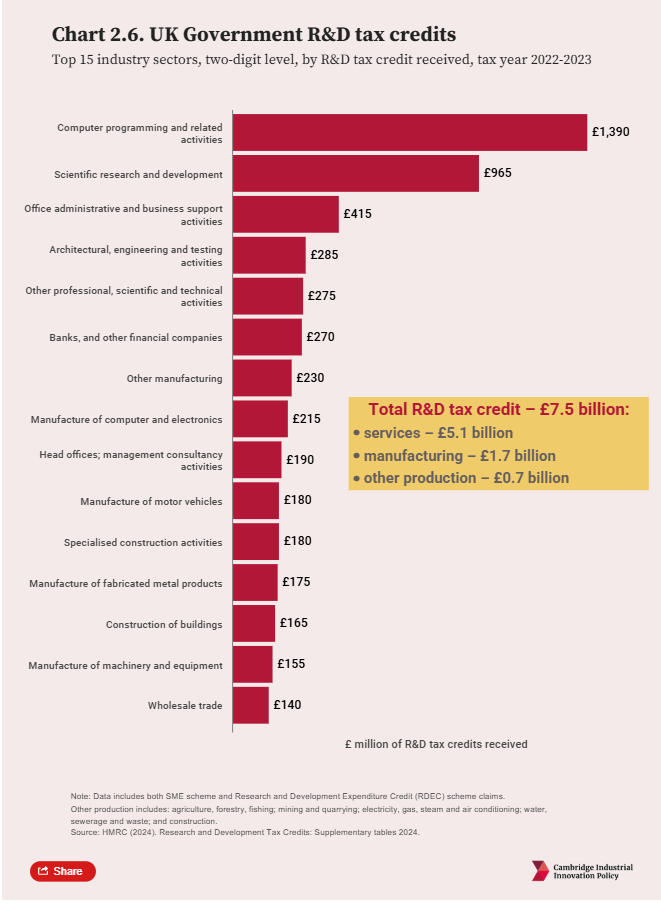
Figure 4: UK Government R&D tax credits: Source.
Britain has already used tax carve-outs extensively in the hope of juicing capital investment, with little progress as far as manufacturing is concerned.
More large-scale supply-side reforms generally relate to broader-based tax cuts, pursuing energy abundance, and deregulating the planning system to enable both residential and commercial construction.
More broadly, any tax reductions would have to, at this stage, be complemented by a reduction in government spending. More likely, taxes on the average earner will have to rise relative to those on high-income earners, who are indeed taxed at high rates: in short, it would have to become more regressive. The alternative is wealth taxes, but this is largely a no-go zone for anyone to the right of the centre-left. This is partially down to ideological reasons, but also a possibly well-founded view that such taxes raise little and spark capital flight.
Then there is energy. On some level, the British energy regime is very constrained. There are levies, carbon taxes and a ridiculously high effective tax rate on oil and gas exploration. But it’s worth acknowledging that the government does not control regulation (Ofgem), the grid’s buildout (NESO) or generation, where there is next to no state ownership at all.
The modern electricity strategy has been hailed as the harnessing of market forces over state direction, and to some degree, this is true. Contracts-for-difference, though an effective subsidy, are private law contracts and were promoted sincerely as a free-market solution to building generation. The wildly expensive nuclear buildout we have is financed not by the state, but by the market.
They may well be constrained by onerous regulation, but non-state-backed nuclear power is expensive in the United States, and indeed most places. No large nuclear fleet has been rolled out without government funding and direction, and to do so would be wildly expensive. Our current buildout is clearly making nuclear power look bad.
Certainly, while deregulation would improve the prospect of a productive electricity system, it will not unwind high prices particularly quickly. The country with arguably the most desirable electricity system in Europe is France, and it was built and is maintained purely through state ownership and investment.
It is also key to point out that, while energy is a significant bottleneck, it is only existential for around 25% of manufacturing GVA. As shown below, most of manufacturing finds high energy prices undesirable, but likely finds lack of capital investment and overproduction from other parts of the world a much larger issue.
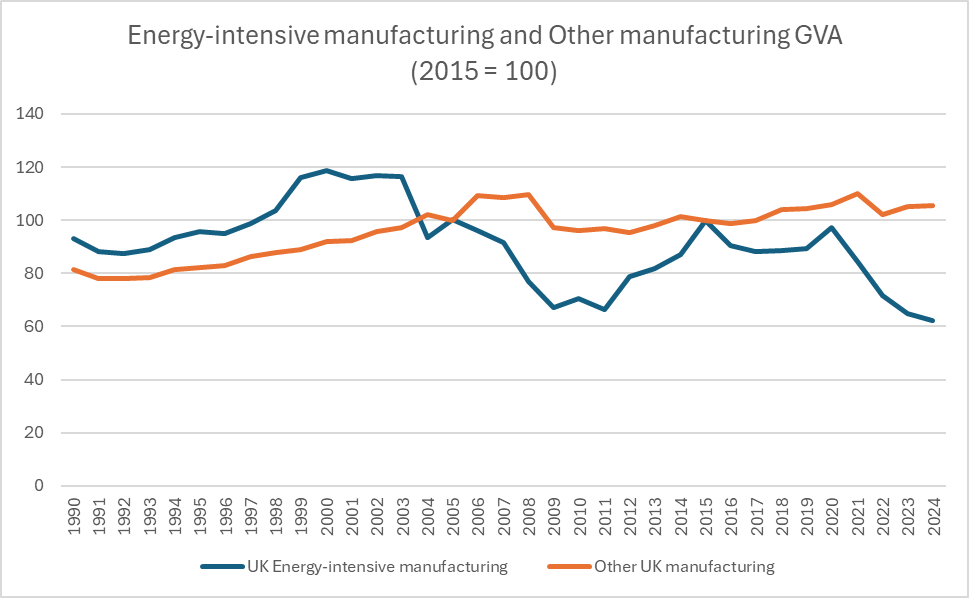
Figure 5: Energy-intensive manufacturing and other manufacturing GVA (2015 = 100). Source: ONS.
The supply-side reformers are on their surest footing when talking about the debacle of British housing, which ties heavily into planning. These are areas where I am far from an expert, and where I imagine market liberalisation would be most impactful. Certainly, the constrained housing supply in productive urban areas has created a counterintuitive situation where the youngest and most dynamic people are net-emigrating to the suburbs and the country, as shown below. In fact, in 2023, the only age group that was net-migrating to urban areas was 15-19 year olds, down largely to higher education.
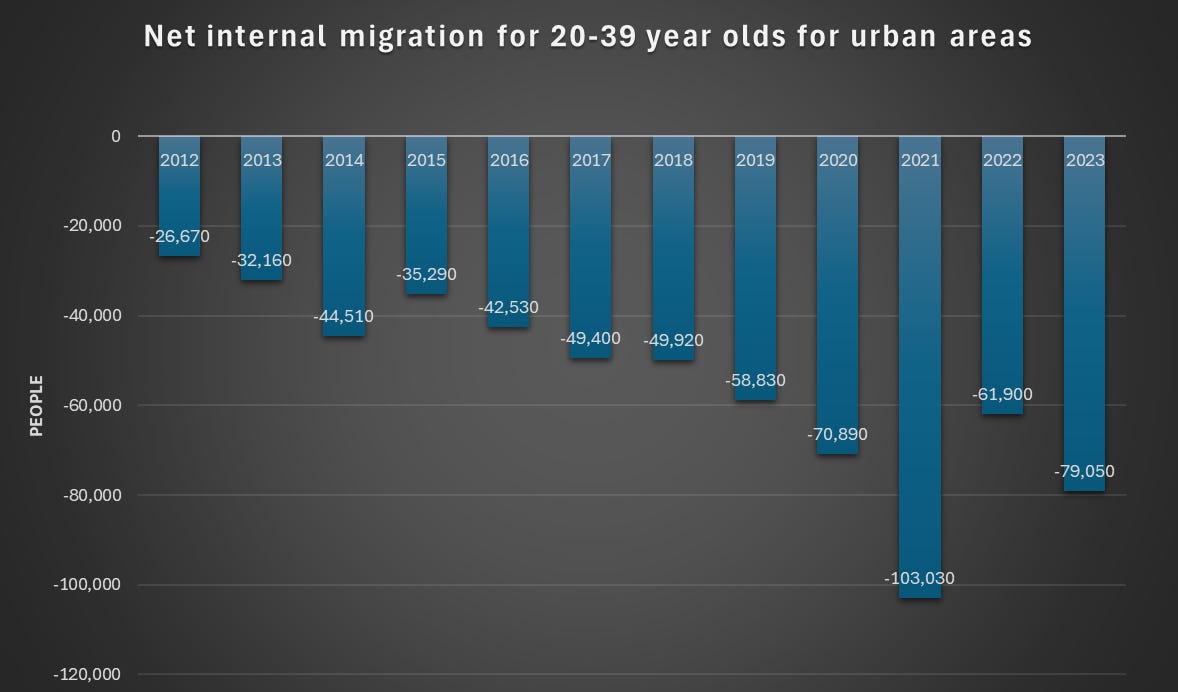
Figure 6: Net internal migration to and from urban areas for ages 20-39. Source: ONS.
There are certainly supply-side reforms that could correct perverse incentives. For example, business rates currently tax the productive use of commercial property and land, and this could be replaced by a commercial land value tax.
This should demonstrate my support for supply-side reform. However, the most immediate supply-side interventions, like full expensing and tax credits, are not a panacea.
Direct investment for equipment and infrastructure (not skills, innovation, redistribution or decarbonisation)
Direct intervention in industry is already accepted by the majority in Britain. While British Steel is set to be nationalised, the fabricated steel maker Sheffield Forgemasters was nationalised in 2021. After four years of nationalisation, the cost of the purchase and subsequent investment was £400 million. As far as I know, no political party objects to the Conservative government’s 2021 decision.
The UK already spends a lot on things that could be called industrial policy. In 2021, it spent £62 billion, or 2.7% of GDP, on broad support to the private sector. We spend more on tax expenditures than our EU counterparts, and less on government-backed loans and state-backed venture capital. A big chunk of these tax expenditures is capital allowances and relief for small businesses and R&D spending. The UK also spends significantly more on supporting ‘jobs and skills’ than other countries, as evidenced by programmes like the Employment Allowance for SMEs and the Lower Profits Limit.
In 2021, the government spent £7 billion on grants. This puts my proposed £1 billion grant scheme for machine tools into context. It would be a notable commitment, but very much inside the realm of policy reality.
The problem with current UK spending seems to be that it is untethered from any clear strategy. It is propping up employment through providing employment-related exemptions for the smallest businesses and providing tax breaks on R&D relief. Running parallel to this is the money earmarked for “Green” infrastructure, including up to £20 billion on carbon capture and storage over 25 years.
This spending should be reviewed and scrutinised, with the aim of making significant savings. Besides pocketing the change, money could be reinvested in grant and loan schemes that specifically target capital equipment to boost industrial capacity. Whether a radical government ends up spending more or less on industrial investment is something that can be argued later. As Mathew Kirtley has brilliantly argued, the vast majority of government excess spending is in entitlements, not investment.
My view is that the vast bulk of this investment should be geared away from decarbonisation, redistribution and speculative innovation, and towards infrastructure and capital equipment to improve energy and industrial capacity.
This would support a wider aim to overturn years of stagnation and get industrial GVA up in inflation-adjusted terms, while increasing manufacturing’s share of GDP from its paltry 8% to something more in line with our productive European neighbours (10-14%). Subsidising machine tools would be a key component of this.
Some might ask if there is not sufficient demand for capital investment, why not attempt to boost demand via supply-side reform? The problem is that the dearth of capital investment in manufacturing is itself constraining supply and deterring investment. A car manufacturer, for the most part, is an assembler as far as manufacturing is concerned. Unless they are merely avoiding tariffs and sending completely built units (CBUs) to their plant, they need a strong ecosystem of local machine shops to supply components and spare parts.
Currently, machine tool consumption in the UK is stagnant and well below that of comparable economies like France. What is more, the average age of a machine tool engineer is high, and retirements are going to start eating into the workforce soon. Currently, shops are unable to train new staff or invest in new equipment due to capital constraints.
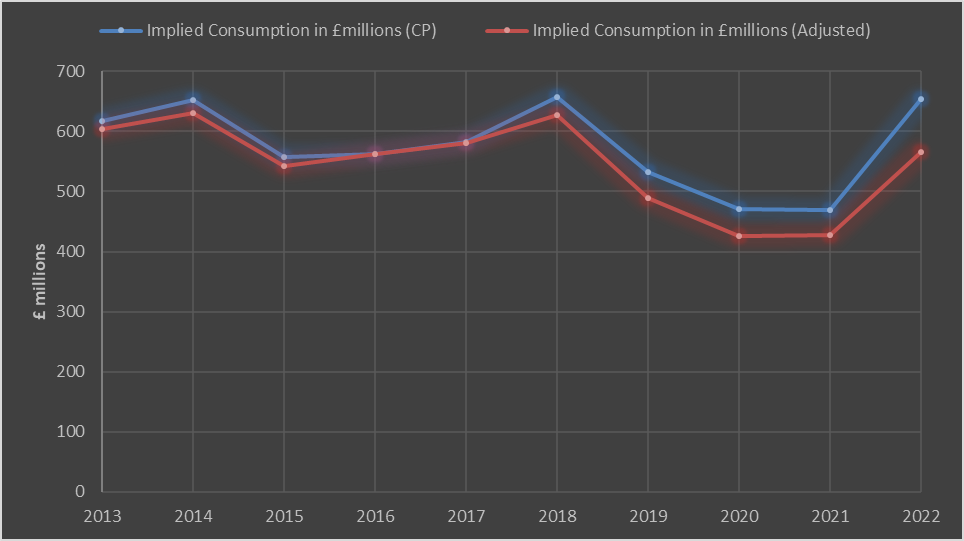
Figure 7: UK machine tool consumption. Source: CECIMO.
The manufacturing startup Isembard, providing evidence to the government, noted that existing debt finance options for such equipment are too expensive. Machine tools are often treated as risky purchases, with lenders demanding deposits of up to 30% and payback periods for as short as three years. Given the ructions of global manufacturing, investing in new equipment is very risky for a small machine shop.
This industry feedback should demonstrate that, even with capital allowances already in place, equipment financing in Britain is challenging. It is here where government-backed lending could play a substantial role. There is no equivalent to Germany’s KfW Bank and regional banks, which offer relatively generous loans. The National Wealth Fund has an annual lending capacity of about one twentieth of KfW.
While such a vehicle could be a powerful tool, it would depend on clear direction, and not confusing the primary objective of increasing industrial capacity and manufacturing value with redistribution, decarbonisation or employing people for its own sake.
The uncertainty of global manufacturing, particularly concerns of being unable to compete with other countries’ mercantilism, and pessimism about the UK, discourages investment and keeps intermediate manufacturing weak, at the same time as the workforce is becoming geriatric.
Supply-side reforms will be necessary, but the situation is pretty dire, and with relatively little direct investment, we could significantly improve our position. An industrial base with double the purchasing power for machine tools would immediately be more attractive to domestic and foreign investors.
Industrial policy, meaning the use of targeted government investments into specific industries, is too often held as an alternative to supply-side reforms, but we are going to need both in the coming decade.
Well written
I think part of the reason people feel so strongly about supply-side liberalisation in particular is that it seems so stupid: we are currently preventing people from doing the things we should want (building houses, producing energy, producing chemicals, etc.) through punitive tax and regulation. This is self-imposed. We control these policies. We could stop actively preventing these good things. Instead of restricting supply while subsidising demand more and more, we could end this cycle and saving taxpayers billions.
Add to that argument some Hayekian caution of industrial policy and add to that the public choice caution of industrial policy, supply-side reforms seem like the low-hanging fruit that a serious government would force through.
That said, I find your essay persuasive. We still have world-class expertise. Many of them will retire soon, often without successors. Moving quickly on good policy right now is highly important. The supply-side argument given above understates how difficult actually making these changes would be. Spending money to protect high GVA industries is achievable in our current political environment. We shouldn't let the perfect (supply-side reform plus highly-competent industrial policy) be the enemy of the good (highly-competent industrial policy).