

Another year, another round of local elections. While the Labour government embarks on a round of Palace infighting, Reform UK has established itself as the clear favourite to be the largest party come the next election, though currently, they are not on course for a comfortable majority. While the Tory Party has moved faster in strict policy terms on issues like energy, Reform is now staffing its policy unit, meaning we can expect more meat on the bone in the coming months.
Being somewhat narrow-minded, I am keen to see how far they go with the concept of ‘Reindustrialisation.’ Robert Jenrick, Reform’s prospective chancellor, has said, ‘Reform has a distinctive economic policy which is not just reheated Thatcherism.’ Both he and Nigel Farage have invoked ‘reindustrialisation’ as a critical component of their wider economic agenda.
Cynics would say this is just fashionable signalling. After all, every political party claims to have a bias towards production, regardless of how they act in office. Nevertheless, Reform’s support is to a great extent built on those areas of England where manufacturing and production are most important.
Reform is the closest thing to an industrial party
Based on NowCast, Reform is expected to do very well in constituencies with large numbers of manufacturing jobs. When comparing the latest projected Reform vote share on NowCast with the number of manufacturing and mining jobs, there is a clear positive correlation.
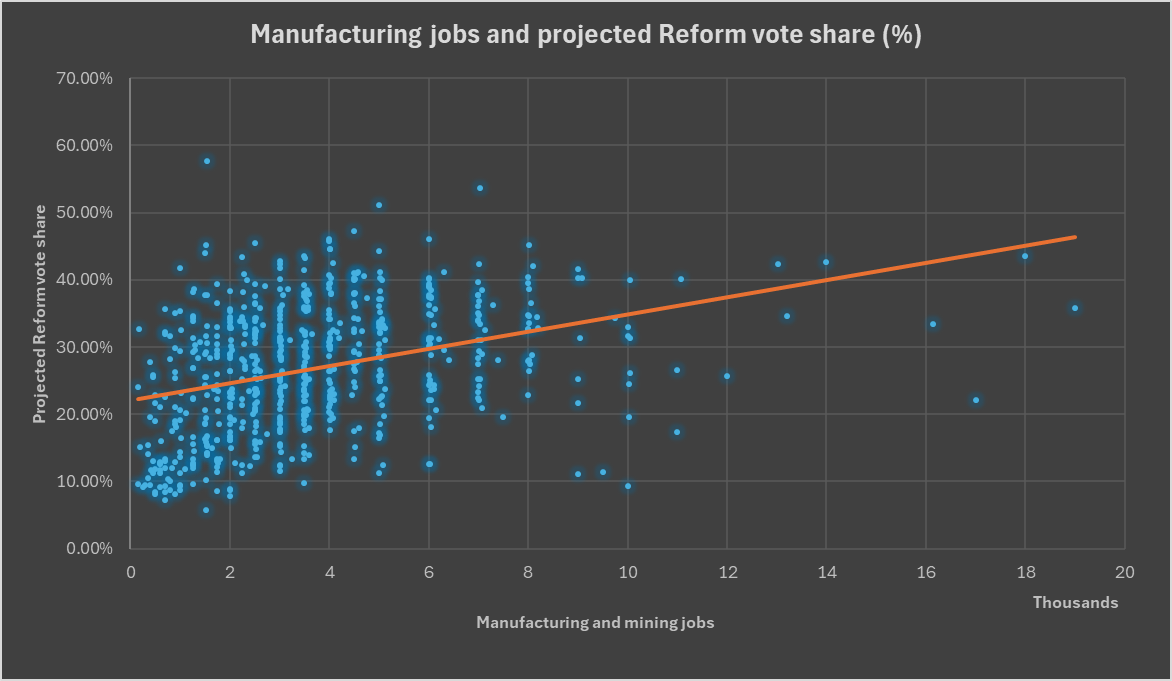
Figure 1: Reform UK’s projected vote share (12/04/2026) and number of manufacturing and mining jobs by constituency. Sources: NOMIS and NowCast.
While this trend does not confirm that Reform must build its entire economic platform around reindustrialisation to win re-election, it suggests the Party, if it does get in, will not be able to afford a laissez-faire drop in manufacturing employment or output. At least publicly, they will not be able to embrace the cavalier attitude of established whigs like Daniel Hannan.
At a more granular level, the Party is currently trailing Plaid Cymru by just 2% in Aberfan Maestag, Stephen Kinnock’s seat and the heart of Welsh steel production. They are a close second to the SNP in Alloa and Grangemouth, where a major refinery was closed in 2025. They are set to romp home in Alyn and Deeside, where there are two paper mills and one large cement kiln. Brigg and Immingham, the home of the Humber oil refinery, are also in their sights.
They are also set to take Beverley and Holderness in the North East, home to Mitsubishi Chemical Group’s UK division and Ineos’s Saltend plant. They are also set to take Stoke-on-Trent Central, the home of Goodwin PLC, and Derby South, home to Rolls-Royce’s primary British factory. While the North West is looking more contested, they are only 6% off in Ellesmere Port. They are set to take Washington and Gateshead South, the home of the Nissan plant in Sunderland.
By contrast, Reform is expected to have little to no constituency representation in London or the inner cities. The Liberal Democrats are expected to have very little representation in the industrial heartlands.
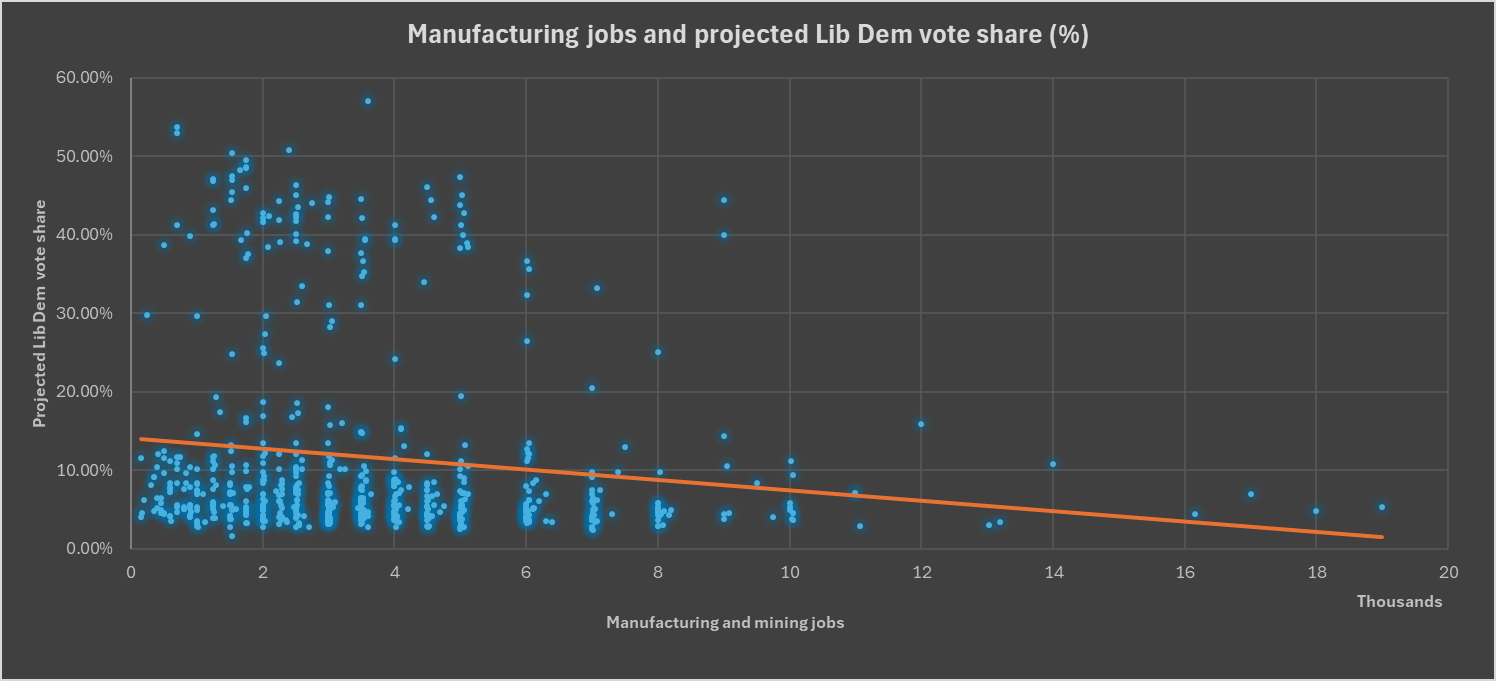
Figure 2: Lib Dem projected vote share (12/04/2026) and number of manufacturing and mining jobs by constituency. Sources: NOMIS and NowCast.
The same goes for the Greens, who are primarily an urban party. Meanwhile, the Labour and Tory parties are fairly neutral.
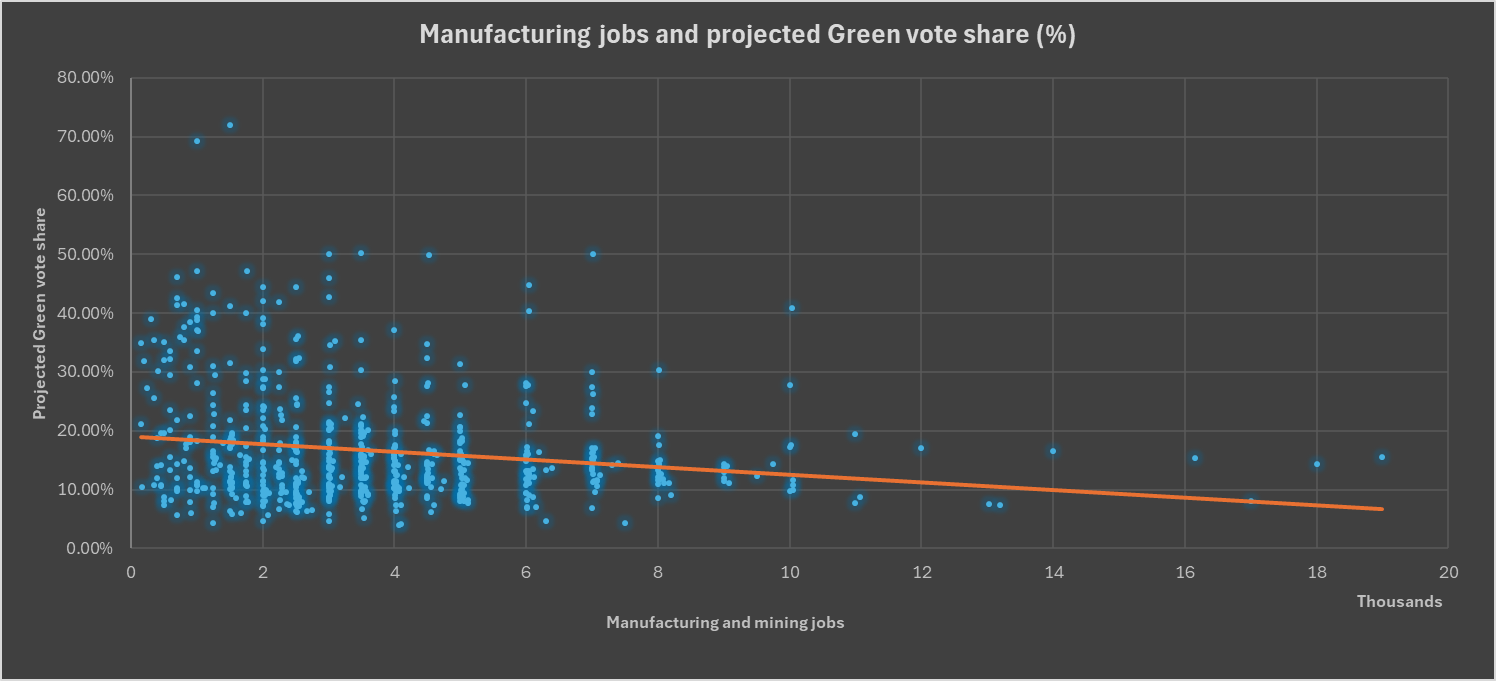
Figure 3: Greens’ projected vote share (12/04/2026) and number of manufacturing and mining jobs by constituency. Sources: NOMIS and NowCast.
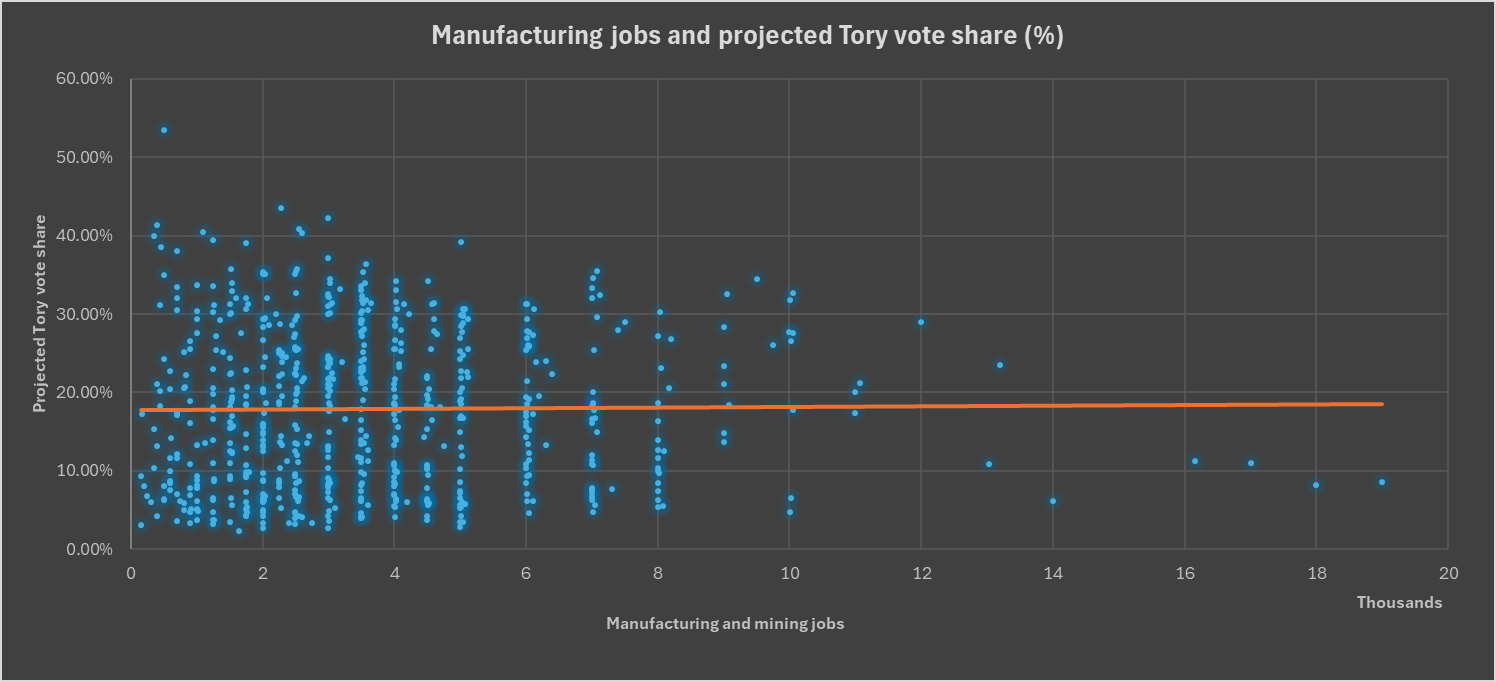
Figure 4: Tory projected vote share (12/04/2026) and number of manufacturing and mining jobs by constituency. Sources: NOMIS and NowCast.
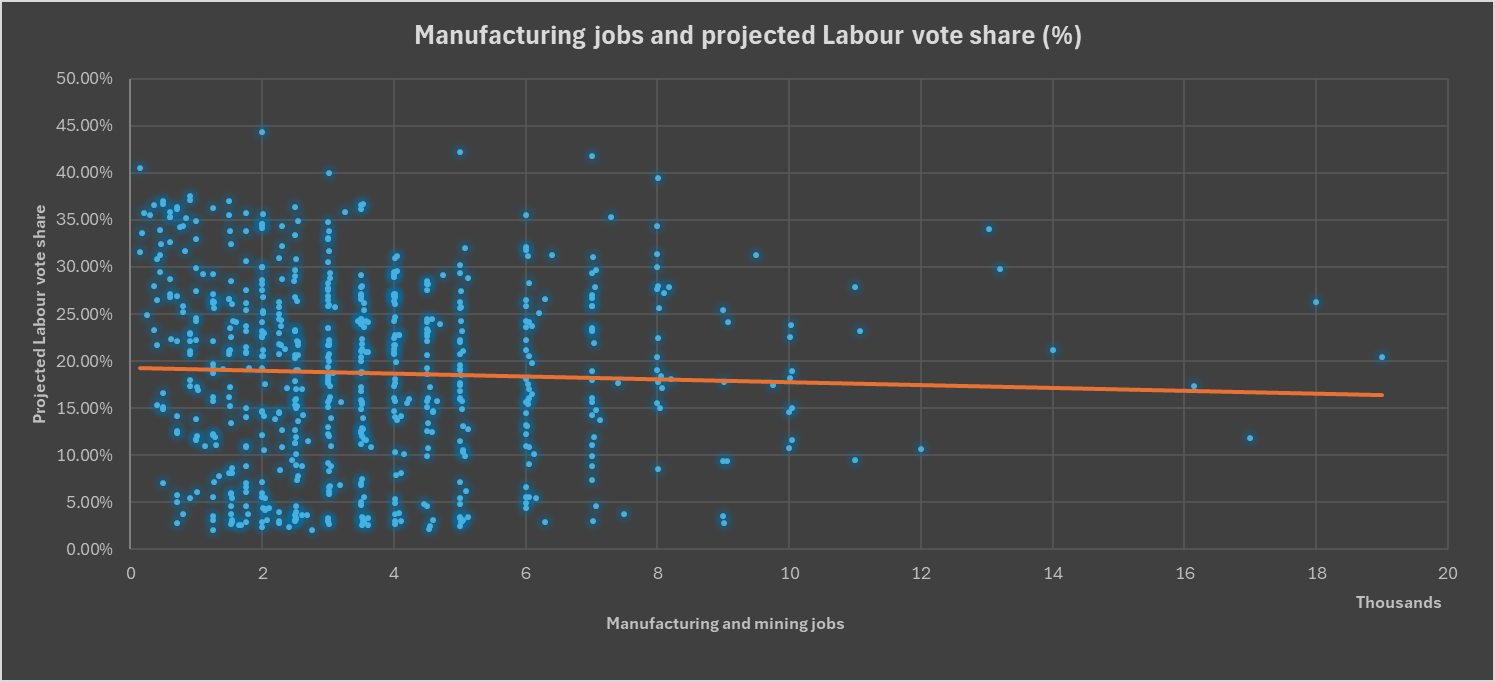
Figure 5: Labour projected vote share (12/04/2026) and number of manufacturing and mining jobs by constituency. Sources: NOMIS and NowCast.
I am optimistic that Reform will be open to a platform that combines supply-side reforms with a targeted plan for reindustrialisation, which will hopefully remain focused on capital investment, improving productivity and enabling the creation of large companies rather than being marketed as a jobs programme. We can take it as read that there will not be much focus on clean power.
The addition of Jenrick as prospective chancellor is clearly a plus for reindustrialisation. Jenrick has acknowledged the need for a stronger industrial base, and he’s even gone so far as to describe himself as an “anglofuturist.” The addition of Sam Ashworth Hayes as a senior policy advisor is also encouraging.
As ever with Reform, the all-important voice is that of Farage himself. In 2025, he called for the nationalisation of British Steel, signalling that while far from repudiating his Thatcherism, he is not doctrinaire about state involvement in industry. Reform is currently procuring an alternative steel strategy, but there’s little indication of what it will involve.
Caveats
Reform’s reindustrialisation programme is still not fleshed out. There are plenty of good signals indicating they will tack towards some accommodation of economic nationalism within their broader platform of deregulation. However, optimism should be tempered.
Despite Reform’s rhetoric and its popularity in manufacturing hotspots, it would be hubris to think their rise is due to a great interest in reindustrialisation. Policymakers naturally obsess over their area of expertise and like to believe that a party’s success is down to a rise in public consciousness of their subject. This was certainly in evidence among Yimbys during the early days of this Labour government.
There is an argument that Reform is a child of the gradual deindustrialisation of Britain, and the resulting destitution of many formerly prosperous provincial areas. However, it is just as much a party of Southern seaside towns and Essex cul-de-sacs filled with London exiles.
Reform’s engine room, at least as far as I can see, is not filled with unionised steel workers or by engineering professionals, but by shopkeepers and pub landlords. In my case, the local Reform councillor heads an independent tooling shop.
Reform’s political bandwidth will not be taken up by reindustrialisation, but by immigration, entitlement spending, the bond markets, the NHS, and global shocks. It would be hubristic for supporters of a more production-oriented economy to think we should steer a Reform government’s economic agenda.
Many of Reform’s voting base are older, and remember the industrial disputes of the pre-Thatcher era as confirmation that industrial policy is bad. I personally think the problem stemmed far more from the poor relationship between management and unions, which made consolidation impossible. There is an excellent long read on the travails of British Leyland in the Sixties and Seventies, written by Ian Nicholls. It outlines how a debilitating breakdown in relations between unions and management, and the resulting inability to consolidate the sprawling car conglomerate, doomed domestic ownership of automobile manufacturing.
There is also the truth that industrial policy does have a very chequered history, and has been far too blended with other aims. Today, industrial policy papers are focused not primarily on raising productivity or increasing exports, but on spreading jobs outside of the South-East, or hitting climate targets.
One potential challenge I see coming down the track for Reform’s reindustrialisation efforts is, counterintuitively, centring the whole discussion around energy. Now this is somewhat odd, as I have analysed in depth the problems of high energy prices on our foundational industries.
Indeed, about 25% of manufacturing is so energy-intensive that our current price profile is existential. But for the remaining 75%, high energy prices can range from a severe pain point to a marginal issue, with a lack of investment and unfair trade practices by other countries being larger issues.
Another reason not to be too myopic on energy is the simple reality that the British ‘Frankengrid’ (coined by Andrew Sabisky) is not going to be unravelled any time soon. Some levies, such as Renewable Obligation Certificates (ROCs), can be minimised, while private law contracts related to contracts-for-difference (CfD), the main levy going forward, are harder to eliminate. Expanding oil and gas production will be a clear boon for a potential Reform government, but will take time to filter through into improved trade balances and gas prices. Unwinding the pathologies of the grid is going to be a major technocratic effort, with the benefits not seen for years.
Reindustrialists are a very niche tribe.
There is also another potential pitfall, which is the critical view that many “reindustrialisers” take of Reform. Many SDP, Blue Labour and Red Conservative types find Reform unconvincing on economic matters or compromised on other issues, such as the influence of crypto-donors.
This distancing is understandable, but there are a few other options available to these groups. Keeping distance can also be a missed opportunity for such a small clique. Those who support “reindustrialisation” beyond a vague support for the latest industrial policy are a small and disparate tribe; prominent among anonymous X accounts but tiny in the grand scheme of things.
For other causes, the depth of intellectual capital is much greater. There is a fully established ecosystem of wonks obsessed with planning and liberalising the housing market. There is also a well-stocked suite of energy wonks, from the most vituperative net zero sceptics to the most ardent defenders of Milibandism. No such infrastructure currently exists for reindustrialisation.
For those who are particularly interested in British manufacturing, there’s going to have to be some patience with Reform. Some of the challenges, like increasing investment or reducing energy prices, might be easy or hard, but have clear solutions. The global glut in manufacturing capacity caused by East Asian mercantilism does not. France, despite cheap energy, has a stagnant manufacturing base. Germany, despite its much stronger ecosystem, has been in decline in manufacturing terms since 2018.
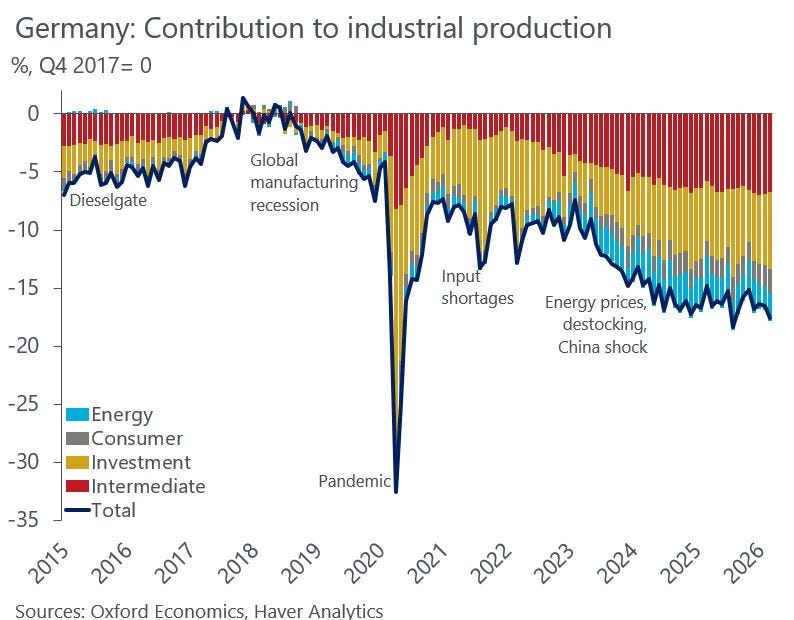
Figure 6: German industrial production 2015-2026, Source: Oxford Analytics.
The Party is also going to have to manage maintaining fiscal credibility while fighting a bloody institutional battle with the civil service, which it has clearly indicated it plans to reform. Any policies related to reindustrialisation are going to have to be clear, limited, and not cancel what will likely be significant planned savings from cuts in government spending.
In summary, Reform UK, at least ideologically, is an open book for reindustrialisation. They are also heavily dependent on the industrial heartland for their parliamentary seats. While there is little policy substance at the moment, this is a natural consequence of a young organisation. The Party should not be dismissed as a potential vehicle for a much more focused industrial policy.
Reindustrialisation requires a very different energy policy than what the UK currently follows. Above all else, energy supply would need to be increased and made more efficient, which means rationalisation of fossil fuel and nuclear construction regulations. I am not sure if Labour or Greens would allow those to happen. Net Zero and renewables require very high investment and thus high energy costs to amortise that investment.
The UK cannot support manufacturing at scale as long as we have energy pricing that is so much higher than the US, China, even Brazil.
A balanced piece. I agree beyond a few select/ headline grabbing interventions (steel nationalisation/ your machine tool spending policy) Reform are unlikely to do much on the industrial strategy front for the reasons you have explained - spending constraints, other political priorities.
That said re-industrial wonks should still get on board, there is certainly space for you within Reform, but make no mistake your job would be more about prevention - stopping "levelling up/ jobs programme think" and coming up with cost-free ways to boost uk industry.