

Choosing an interest, it may seem there are few as likely to create a sense of misery as British manufacturing. I have mentioned plenty of the problems, from expensive energy to a lack of machine tools and robots, to low investment, to global oversupply, to the near-closure of British Steel.
But this should be tempered, as excessive negativity can make the prospect of even a moderate reindustrialisation programme seem like “pie in the sky”. This gives critics of the manufacturing focus an easy argument, that the sector is so badly written off that we might as well focus on what we do best. Some would say that it is financial services, but this sector is increasingly showing limited growth, so instead, the focus should be on creative industries, professional services, and AI-related software.
In this short piece, I’d like to highlight some positive aspects of British manufacturing (not exhaustive), which should give advocates of reindustrialisation some hope for the future.
1: British manufacturing has held up quite well
Firstly, despite all the headwinds, British manufacturing has held pretty steady. This is obviously stagnation, but considering Britain’s very high energy costs, exchange-rate pressures, and sclerotic planning system, the value of the manufacturing base has held up. As seen below, manufacturing GVA rose in inflation-adjusted terms after recovering from the 2008 crash. This has been offset by a major drop in mining and quarrying (mainly North Sea oil and gas), so production has still not reached its pre-crisis peak.
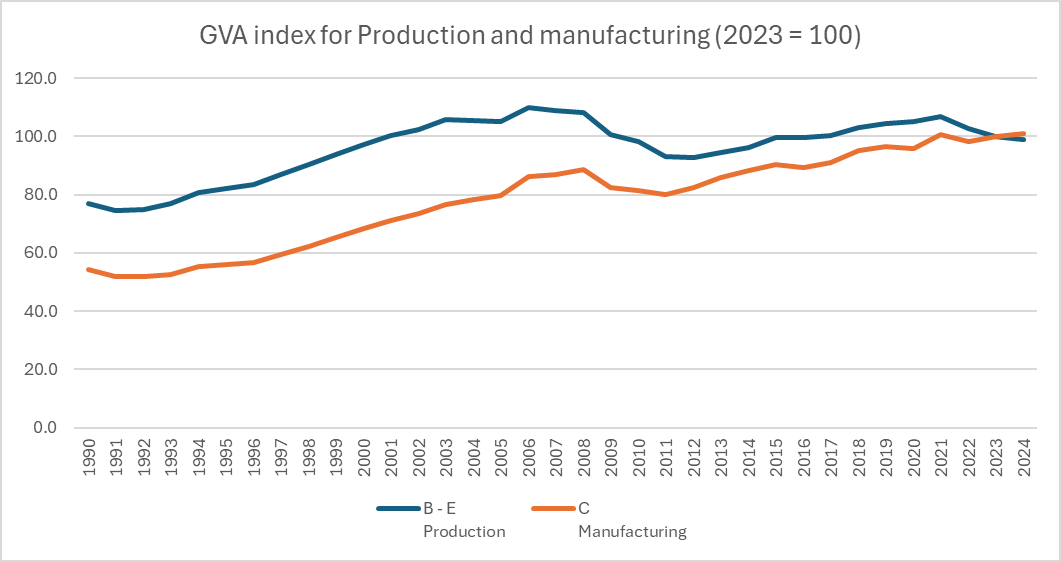
Figure 1: GVA Index for production and manufacturing. Source: ONS
2: Manufacturing investment and employment partially recovered from the 2000s
While the early noughties were a good time for GDP growth in manufacturing, it was horrible from an investment and employment perspective. Following 2008, there was a partial investment recovery in capital equipment. This was not enough to replenish the capital stock lost during the high point of globalisation, but it did improve productivity. Employment also stabilised. While manufacturing employment has continued to decline, the process has slowed significantly over the last 15 years.
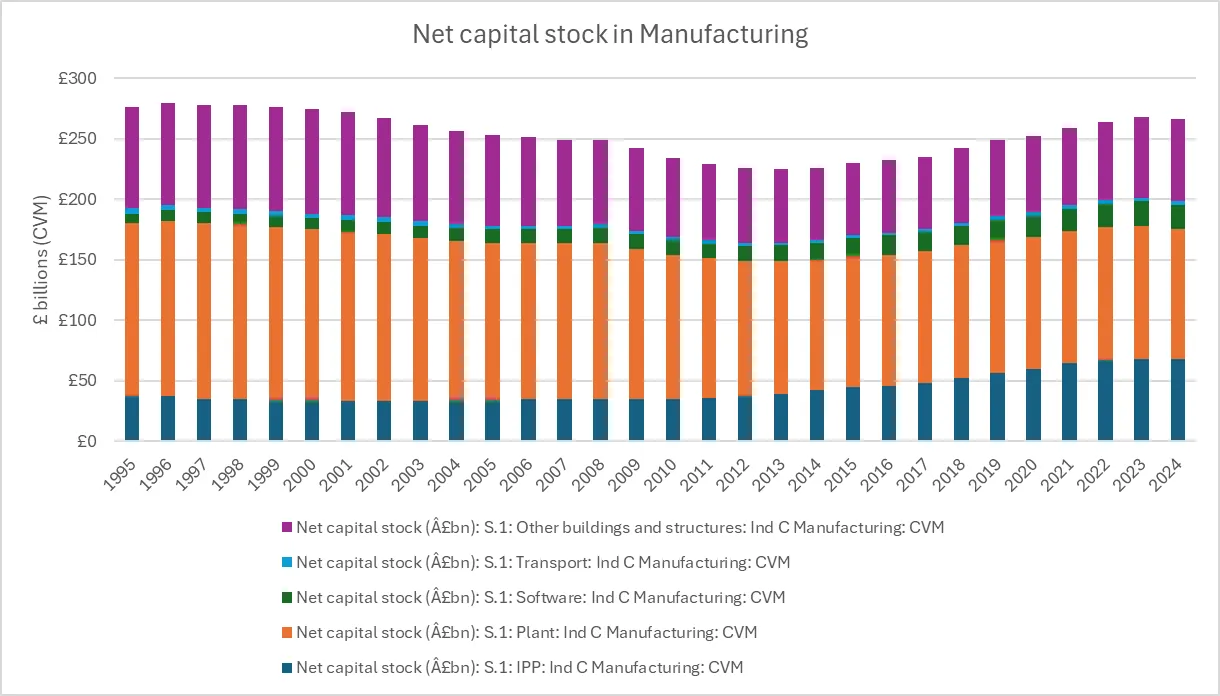
Figure 2: Net Capital Stock for Manufacturing by investment sector from 1995 to 2024. Inflation-adjusted. Source: ONS.
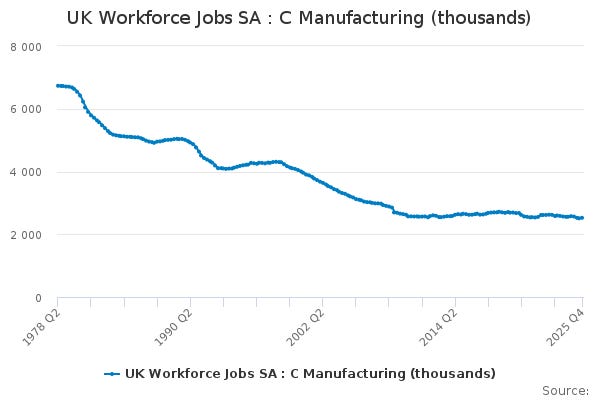
Figure 3: Manufacturing employment. Source: ONS
This tells us that manufacturing’s decline is not some continual process; rather, deindustrialisation is characterised by short periods of acute losses in investment and jobs.
3: Britain’s heavy manufacturing sector last peaked relatively recently
There is a common assumption that British manufacturing peaked in the 1980s and has been on a downward trajectory since. Actually, the industry peaked in the late nineties and early 2000s.
Britain had to adapt to Japan, South Korea, Germany and France, and did so relatively successfully. By 1999, it was the 4th largest industrial base by nominal GVA, a considerable achievement. It’s interesting to me that Thatcherites will die in a ditch saying how they were right to shake off manufacturing jobs, instead of emphasising that they had actually overseen substantial growth in output and value.
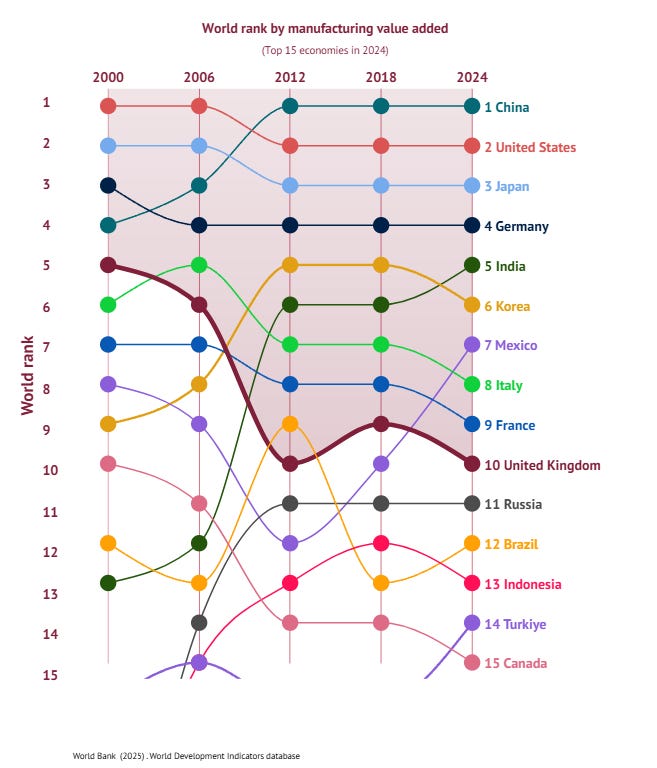
Figure 4: GVA rankings. Source: Cambridge manufacturing dashboard.
Steel production remained high well into the late 90s. Welsh steel production reached its peak in 1997.
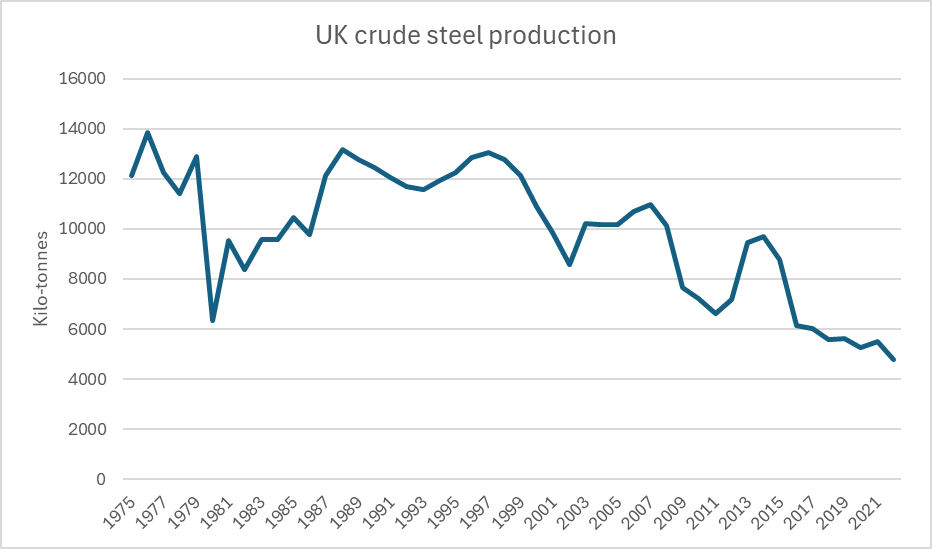
Figure 5: UK crude steel production. Source: ISSB
Steel production per employee reached its apogee in 2015. It has unfortunately declined markedly since then, showing that efficiency improvements are to a large extent dependent on properly maintaining an underlying infrastructure – in the UK’s case, cheap electricity and continual steel demand.
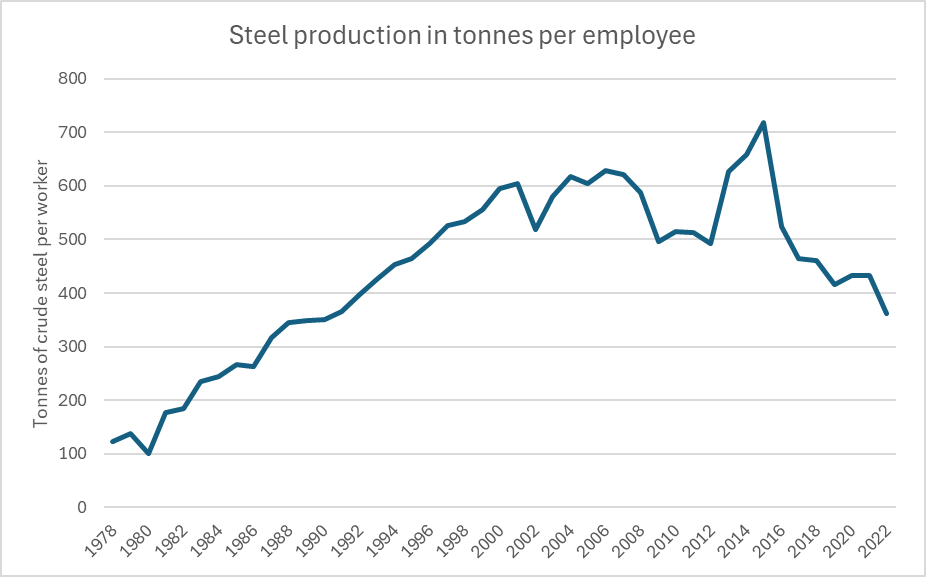
Figure 6: Steel production per employee. Source: ISSB
Looking more broadly at the energy-intensive industries, they peaked in the year 2000.
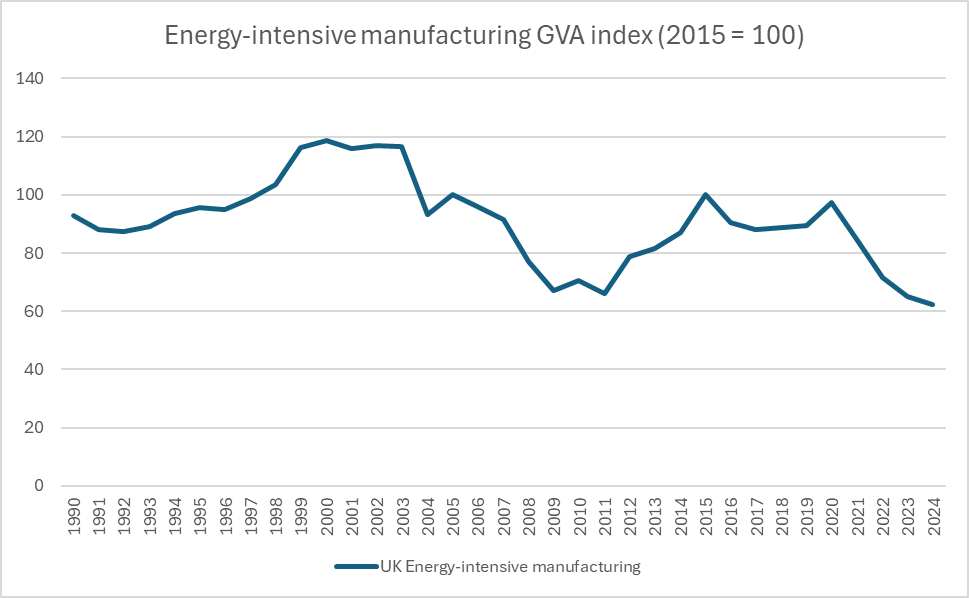
Figure 7: Energy-intensive manufacturing GVA index. Source: ONS.
Britons entering the new millennium would not have shrugged their shoulders at their industrial base declining so markedly in twenty years. They would be horrified.
5: Britain has one of the highest value-added manufacturing bases in the world
Besides the U.S., Britain’s manufacturing base has the highest value-added-to-output ratio of any major economy, meaning a greater share of its output is retained through profits or salaries. A consequence of Britain’s strong currency and challenging environment is that the companies still operating tend to run on stricter financial metrics than their competitors. This might hurt competitiveness when it comes to market share, but from an accounting perspective, British manufacturers perform well.
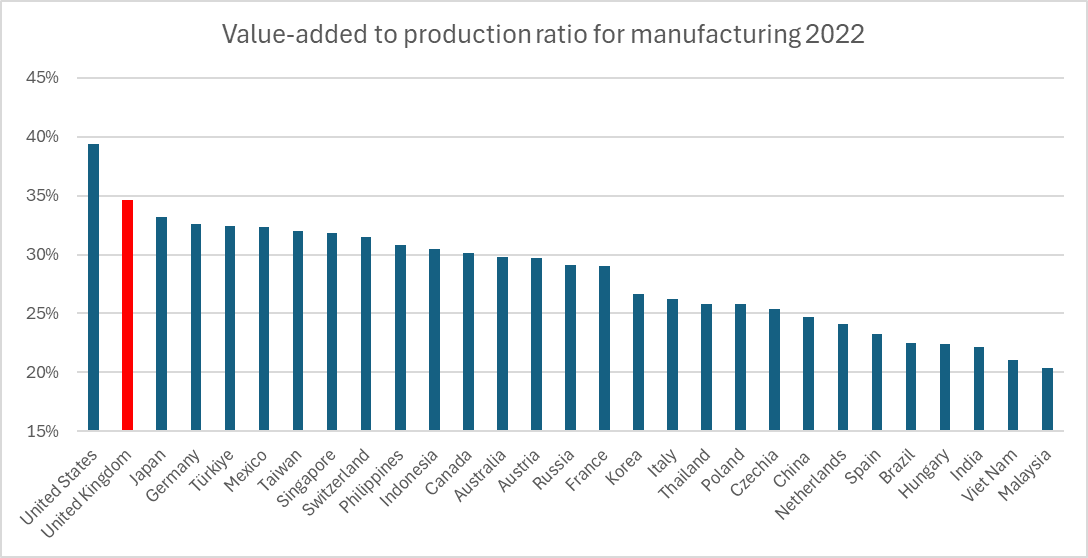
Figure 8: Value-added to production ratio by country. Source: OECD TiVA.
6: Manufacturing is diffuse
Industry is often perceived to be at home far away from the capital. In reality, British manufacturing is split fairly evenly across the regions. We should not see reindustrialisation primarily through the ‘politics of place’ lens. Growth in manufacturing should lead to a broad-based improvement in national productivity growth.
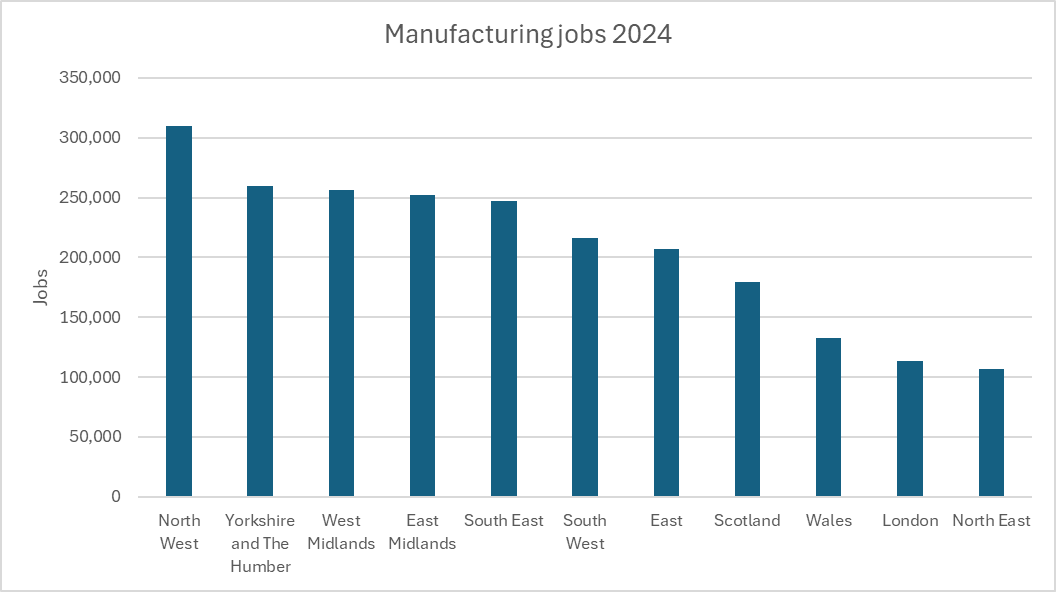
Figure 9: Manufacturing jobs by region. Source: NOMIS.
7: There are still world-leading British manufacturers
There are still many very capable British manufacturers. In aerospace, there is Rolls-Royce, which manages about 12% of global aero engine demand. Martin-Baker makes a majority of the world’s aircraft ejector seats, with the only serious competitor being U.S. giant Collins Aerospace.
In chemicals, Ineos is well known as one of the largest petrochemical companies worldwide. Besides their main petrochemical site in Grangemouth, they have sites in the Humber, Hampshire and Cheshire, dedicated to manufacturing plastics and solvents. Meanwhile, Croda, based in East Yorkshire, is a world leader in speciality lipids.
Beyond the sorry state of primary steel-making, there are many impressive metalworking suppliers. Goodwin PLC, based in Stoke, makes high-end steel castings and refractory products. Another major forging company, founded in 1866 and still going strong, is Somers Forge in Birmingham. Sheffield Forgemasters is a major secondary metal manufacturer, making forged castings for high-value components like nuclear reactor pressure vessels. After being nationalised in 2021, it showed its value by demonstrating an innovative use of electron-beam welding that could significantly reduce the fabrication time for small modular reactors.
Britain’s automotive sector has not done badly. While the industry is largely foreign-owned, its headline GVA performance has been pretty impressive until recently, peaking at £19 billion in 2017. There is also a significant luxury vehicle market. Companies like Bentley, Aston Martin, Lotus and Rolls-Royce (the car brand) all enjoy significant demand in the U.S. and Asia. Despite accounting for 4% of car volume, luxury vehicles account for 12% of the auto industry’s value.
Then you have the extensive military industrial complex, which, despite Britain’s defence procurement challenges, is still one of the deepest defence-industrial bases outside the United States. Below is a list of site names I collected. I am sure there are quite a few missing.
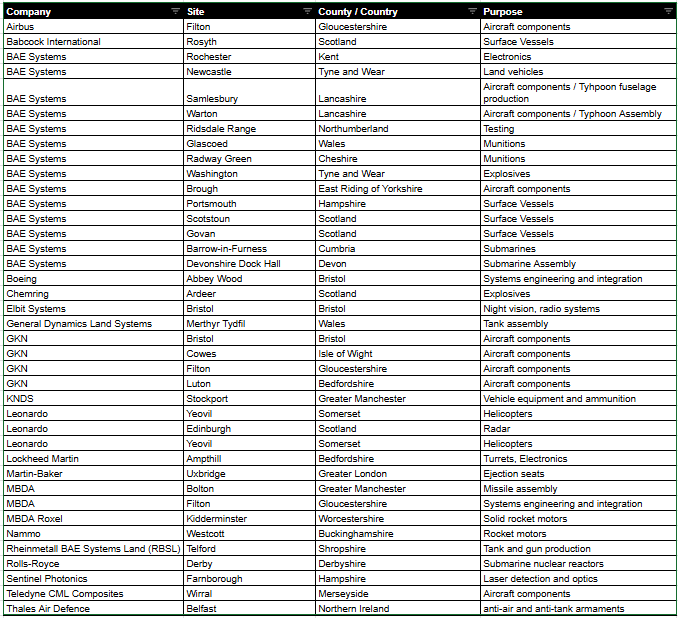
Figure 10: UK military production. Source: Personal research.
Manufacturing is not doing well, but it could have performed a lot worse. As a sector, it retains strong capabilities and was flying high not too long ago. It is worth remembering that Britain still retains substantial industrial capabilities as we push for reindustrialisation.
This was really great - thanks Rian
This is such a valuable contribution. Thankyou